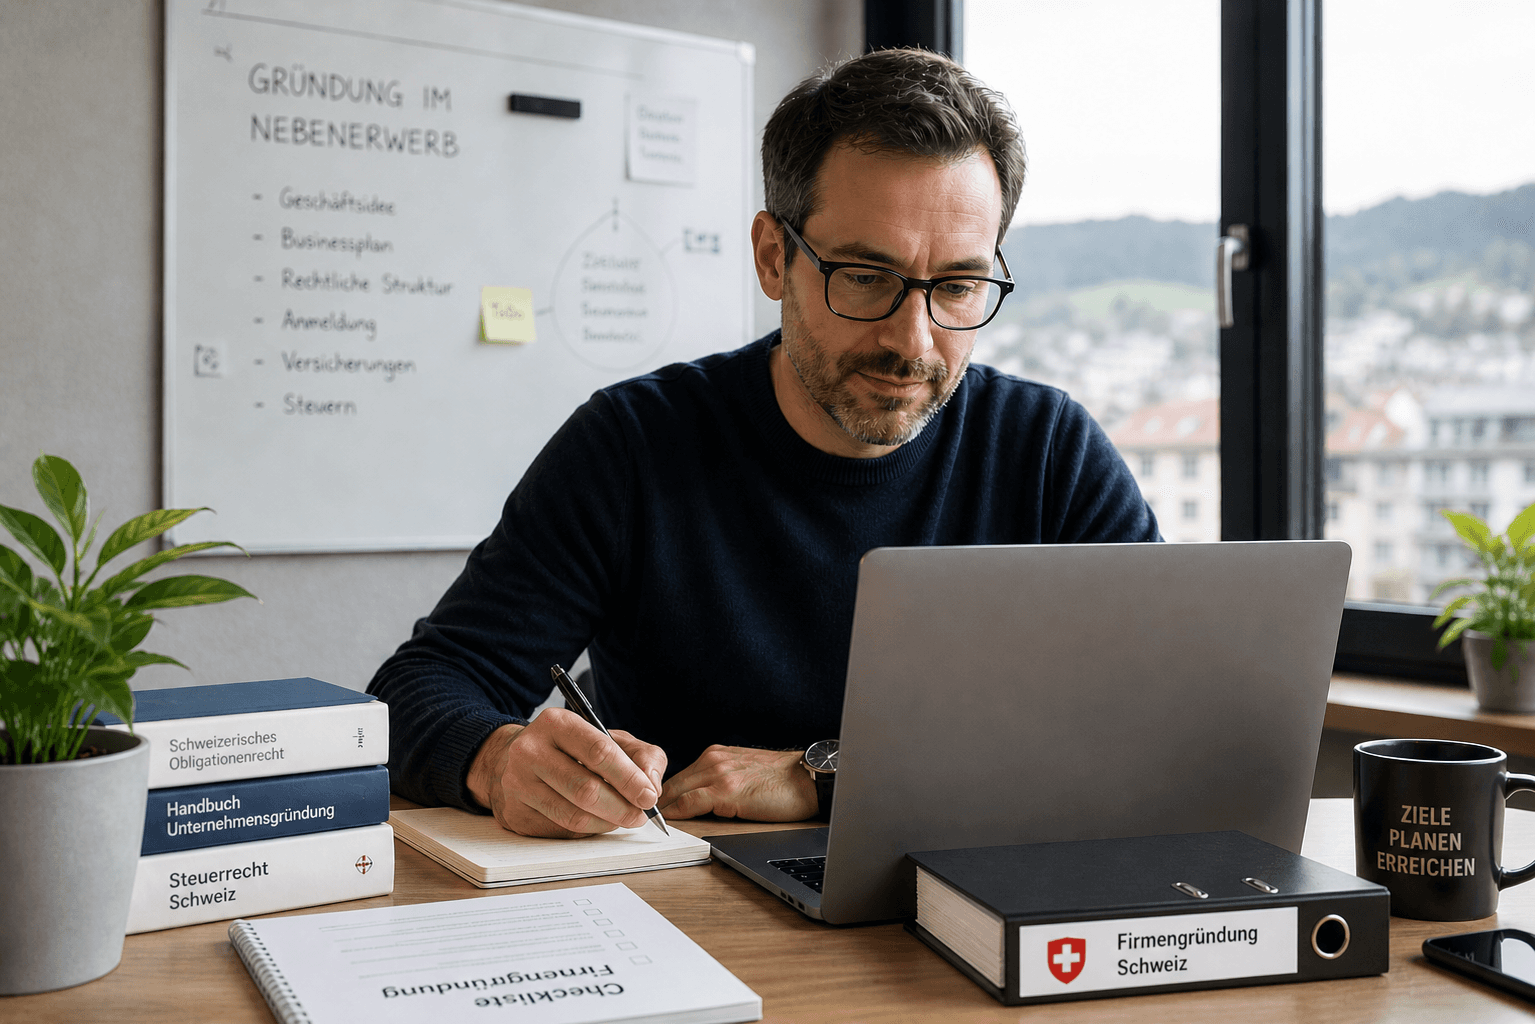
Building your own business alongside your existing job is generally possible in Switzerland. However, it becomes sensitive where your secondary employment conflicts with your employment contract, competes with your employer, or your work performance suffers.
Anyone who wants to found a secondary LLC or stock corporation should therefore not only think about the website, logo, and customer acquisition. Important aspects also include the employment contract, duty of loyalty, legal form, AHV, taxes, insurance, commercial register, and VAT.
Am I even allowed to found a company alongside my job?
Yes. Swiss law does not automatically prohibit founding a company as a secondary occupation. However, the crucial factor is that you safeguard the legitimate interests of your employer. This obligation arises from the duty of loyalty under employment law pursuant to Art. 321a Abs. 1 OR.
The Federal Supreme Court has drawn an important line in this regard. An employee may prepare a subsequent independent activity even during an existing employment relationship. However, it becomes impermissible if the preparation violates good faith, for example, because the employee already competes during the employment relationship or solicits customers or employees (BGE 117 II 72 E. 4a). Preparation may also be permissible in an un-terminated position if the work performance is fully rendered and the legitimate economic interests of the employer are not impaired (BGE 117 II 72 E. 4b).
In short: founding a company is not the problem. It becomes problematic if you economically get in your employer's way in the process.
The duty of loyalty is the most important boundary
The duty of loyalty is the central legal framework for any secondary business foundation. According to Art. 321a Abs. 3 OR, an employee may not perform paid work for third parties during the employment relationship if this violates the duty of loyalty, in particular if the employer is competed with.
This does not mean that every paid secondary activity is prohibited. Secondary employment is generally possible as long as it does not create competition, does not impair the employer's reputation, and your performance in the main job does not suffer. These principles correspond to the official employment law classification of secondary employment (SECO, «Nebenerwerb»).
Therefore, it is not enough to say: "I only do this in the evening." If your secondary employment impairs your performance in your main job or targets the same customer market, it can become legally sensitive under employment law.
When does the secondary company become prohibited competition?
Competition does not exist simply because you become entrepreneurially active. According to case law, a genuine competitive relationship is required. Such a relationship exists if similar services are offered to a completely or partially identical customer base (BGer 4A_50/2021 E. 3.6).
The Federal Supreme Court emphasizes that an employee may prepare a subsequent activity. However, the limit is exceeded if they begin competing during the employment relationship or solicit customers or employees from the employer (BGer 4A_50/2021 E. 3.7).
In practical terms, this means: if you, as an employed marketing consultant, build an online shop for handmade ceramics on the weekend, this is usually less critical. However, if you simultaneously offer the same consulting services for the same target group as your employer, it quickly becomes critical.
Employer resources and business secrets are off-limits
A common mistake when founding a secondary business is using the employer's resources. Work equipment, technical facilities, vehicles, and material of the employer must be handled with care (Art. 321a Abs. 2 OR).
Therefore, you should not use any customer data, templates, software access, devices, email addresses, or internal information of your employer for your own company. Business and manufacturing secrets are particularly sensitive. You must not exploit or disclose such facts that are to be kept secret during the employment relationship. Even after the end of the employment relationship, the obligation of confidentiality remains in place to the extent necessary to safeguard the employer's legitimate interests (Art. 321a Abs. 4 OR).
In practice, the distinction is simple: what you received, developed, or learned for your employer does not automatically belong in your own business.
Do not underestimate working hours, rest periods, and energy
In addition to the issue of competition, there is a second practical limit: your secondary company must not impair your work performance in your main job. If you are permanently overtired in your main job due to customer appointments in the evening, weekend work, or night-time bookkeeping, even an activity that is not competing in itself can become problematic.
With multiple activities, protective provisions of labor law can also become relevant, especially maximum working hours and rest periods. This is particularly important if the secondary employment is time-intensive or physically demanding. The decisive factor is not only what is in the contract, but whether you can continue to reliably fulfill your obligations in the main job (SECO, «Nebenerwerb»).
Check employment contract: reporting duty, authorization, and non-compete clause
Before you found a secondary business, you should read your employment contract carefully. Many employment contracts contain clauses on secondary activities. Such clauses may, for example, provide that secondary employment must be reported or authorized.
You should take such contract clauses seriously. Even if secondary employment is not automatically prohibited by law, a contractual obligation to report or obtain authorization may exist. You should be especially careful if your planned business operates in the same industry, with similar customers, or with similar services as your employer.
The focus is different for post-contractual non-compete clauses. Such a clause only takes effect after the end of the employment relationship. According to Art. 340 Abs. 1 OR, an employee with capacity to act may undertake in writing to refrain from any competing activity after the end of the employment relationship. However, a non-compete clause is only binding if the employee had insight into the customer base or into manufacturing and business secrets and the use of this knowledge could significantly harm the employer (Art. 340 Abs. 2 OR).
For founders of a secondary business, this means: during employment, the duty of loyalty is crucial. After leaving, an effective non-compete clause can additionally become relevant.
Sole proprietorship, LLC, or stock corporation: which legal form fits secondary employment?
Many start a secondary business as a sole proprietorship. This is simple, inexpensive, and administratively lean. A natural person who runs a business only needs to register their sole proprietorship in the commercial register if a turnover of at least CHF 100,000 was achieved in the last financial year (Art. 931 Abs. 1 OR). Voluntary registration is possible (Art. 931 Abs. 3 OR). The sole proprietorship is particularly suitable for smaller, personal activities without a large capital requirement (KMU.admin.ch, «Rechtsform: Einzelunternehmen»).
In the case of a sole proprietorship, it is important to note: you are not separate from your business. This can be practical for small, low-risk activities. For larger liability risks, investments, or multiple partners, an LLC or stock corporation may make more sense.
The LLC is a person-oriented capital company. In principle, only the company assets are liable for its liabilities (Art. 772 Abs. 1 OR). The share capital is at least CHF 20,000 (Art. 773 Abs. 1 OR). The stock corporation is also a capital company in which, in principle, only the company assets are liable for liabilities (Art. 620 Abs. 1 OR). The share capital is at least CHF 100,000 (Art. 621 Abs. 1 OR).
This limitation of liability is an important advantage of LLC and stock corporation. However, it does not mean that founders never bear personal risks. Personal guarantees, joint liability, private contracts, or breaches of duty as a governing body can still have personal consequences. Especially in the case of bank loans, lease agreements, or important supplier contracts, it is therefore worth taking a close look at the signatures and personal securities.
In practice, this means: the sole proprietorship is often suitable for an uncomplicated start. The LLC can make sense if you want to limit liability risks, appear more professional, or later integrate employees and partners. The stock corporation is usually more suitable for capital-intensive or strongly growth-oriented projects.
Bookkeeping: even "on the side" you need order
Even if you "only on the side" found a business, you need clean bookkeeping. Sole proprietorships and partnerships with less than CHF 500,000 turnover in the last financial year must at least keep records of income, expenses, and the asset situation (Art. 957 Abs. 2 OR). From CHF 500,000 turnover, sole proprietorships and partnerships are subject to the ordinary duty of bookkeeping and financial reporting (Art. 957 Abs. 1 Ziff. 1 OR).
Legal entities, i.e., in particular LLC and stock corporation, are subject to the duty of bookkeeping and financial reporting regardless of turnover (Art. 957 Abs. 1 Ziff. 2 OR). These principles also correspond to the official classification for the legal form of a sole proprietorship (KMU.admin.ch, «Rechtsform: Einzelunternehmen»).
Especially when founding a secondary business, it is worth cleanly separating private and business finances from the start. This facilitates AHV, taxes, insurance, and later also a possible conversion or expansion.
AHV and social security: employed and self-employed at the same time?
Yes, that is possible. According to Art. 12 Abs. 2 ATSG, self-employed persons can also be employees at the same time if they earn corresponding earned income. This is precisely the case for many secondary business foundations.
A self-employed person is someone who earns earned income that does not represent remuneration for work performed as an employee (Art. 12 Abs. 1 ATSG). In practice, the crucial factors are primarily the entrepreneurial risk, having one's own work organization, and a visible market presence. The assessment is not made across the board for a person, but with reference to the specific activity. It is therefore possible to be an employee in the main job and, in addition, to be considered self-employed for another activity (AHV/IV-Merkblatt 2.02, «Beiträge der Selbstständigerwerbenden an die AHV, die IV und die EO»).
There is a special AHV rule for minor self-employed secondary activities. Contributions from income from a secondary self-employed activity that does not exceed CHF 2,500 in the calendar year are only levied at the request of the insured person (Art. 19 AHVV). For the status in 2026, the official AHV/IV information confirms this threshold of CHF 2,500 (AHV/IV-Merkblatt 2.02).
Attention: on the internet, you can still find older figures of CHF 2,300. For the status in 2026, the threshold of CHF 2,500 is decisive according to the audited official sources.
As soon as your secondary employment goes beyond this or the activity grows seriously, you should clarify the registration and recognition with the compensation office at an early stage. For recognition as a self-employed person, documents such as invoices, contracts, offers, business stationery, or other receipts for the activity undertaken are typically relevant (KMU-Portal des Bundes, «Selbstständigkeit: ein Leitfaden»).
Taxes, VAT, and insurance belong on the checklist
Income from secondary employment is relevant for tax purposes. In the case of a sole proprietorship, the profit generally flows into your personal situation. In the case of an LLC and stock corporation, the company is its own legal entity, which is structured differently for tax and social security purposes.
An important point is VAT. Companies based in Switzerland may generally be subject to VAT if they perform a self-employed professional or commercial activity, act externally under their own name, and sustainably earn income from services. For most companies, the turnover limit of CHF 100,000 from services in Switzerland and abroad is relevant, provided these are not exempt from tax (ESTV, «MWST-Steuerpflicht»).
This CHF 100,000 limit is practically important because it also appears in the obligation of sole proprietorships to register in the commercial register. Nevertheless, these are two different topics. The commercial register entry concerns the registration of your sole proprietorship. VAT concerns the question of whether you have to account for VAT. If your secondary employment grows towards CHF 100,000 turnover, you should therefore examine both topics separately.
You should also not underestimate insurance. Depending on the activity, professional liability, public liability, accident insurance, daily sickness benefits, or additional pension solutions may become important. If you employ staff, additional social security obligations arise. The specific design depends heavily on the industry, legal form, and risk profile.
Therefore, for founding a secondary business: start lean, but not blind. The more your project appears externally, the more turnover is generated, and the higher the liability risk, the more important clean structures become.
Communication with the employer: openness can reduce risks
Not every foundation must automatically be reported to the employer. However, if your employment contract provides for a reporting or authorization obligation, you should adhere to it. Even without an explicit clause, transparent communication can make sense if the activity is close to your employer's business area or becomes time-intensive.
You do not necessarily have to disclose your entire business idea to your employer. However, a clear distinction is useful. You should be able to explain that you do not use working hours, do not use employer resources, do not solicit customers or employees, and that no competition takes place.
Caution is especially advised for activities in the same industry. What looks like "harmless preparation" to you can look like a threat to their economic interests from the employer's perspective.
The most important starting question: can you cleanly separate?
The most important question before founding a company as a secondary occupation is not only: "Do I have time for this?" The better question is: "Can I legally and practically separate my project cleanly from my job?"
If you continue to perform your work unchanged, do not use business secrets, do not target customers of your employer, do not use the employer's infrastructure, do not violate any contractual authorization obligation, and keep an eye on the labor law rest periods, founding a secondary business is legally significantly less risky.
On the other hand, if your project operates in the same market, concerns the same customers, or builds on know-how from your job, you should examine more closely before starting whether employment contract or legal boundaries are exceeded.
Summary
To found a secondary LLC or stock corporation is generally permitted in Switzerland. The most important boundaries arise from the duty of loyalty to the employer under Art. 321a OR. Preparatory actions are permissible as long as you do not compete with your employer, do not solicit customers or employees, do not use business secrets, and your work performance does not suffer (BGE 117 II 72 E. 4a, BGer 4A_50/2021 E. 3.7).
Before starting, you should check your employment contract, especially for clauses on secondary activities and non-compete clauses under Art. 340 OR. Regarding the legal form, the sole proprietorship is often the simplest entry, while LLC and stock corporation become interesting primarily for liability risks, growth, and a professional appearance.
For AHV and social security, it is important that you can be employed and self-employed at the same time (Art. 12 Abs. 2 ATSG). For minor self-employed secondary activities up to CHF 2,500 per calendar year, contributions are only levied on request (Art. 19 AHVV). For higher amounts or serious market entry, you should clarify recognition with the compensation office at an early stage.
Commercial register, bookkeeping, taxes, VAT, and insurance also belong on the checklist from the start. The best principle is: founding alongside a job is possible. But the closer your secondary employment is to your employer's business and the more your project grows, the more cleanly you must separate.